When my parents needed cash to bridge a gap between planting season and slow-paying customers, they borrowed. Sometimes it was a traditional bank loan, sometimes it was a line of credit tied to the business. That lesson stuck with me: borrowed money can feel like income in your bank account, but the IRS treats it very differently.
If you are drawing from a home equity line of credit (HELOC) and wondering whether the money is taxable, here is the clear answer and the few situations where it can get complicated.
HELOC proceeds are usually not taxable
HELOC proceeds are generally not taxable income when you receive them. A HELOC draw is a loan. You are receiving cash with a legal obligation to pay it back, often secured by your home.
That is the key tax concept: income increases your net worth without an obligation to repay. A HELOC draw increases your cash, but it also increases your debt by the same amount. Net worth does not go up solely because you borrowed.
Does it matter what you use the money for?
Using a HELOC for renovations, tuition, credit card payoff, startup expenses, or even investing does not change the basic tax treatment of the proceeds. The use of the money may matter for other tax items (especially interest), but the cash you draw is still borrowed money.
Where it shows up on your tax return
Most of the time, it does not.
- You do not report the draw as wages, and it will not show up on Form W-2.
- You do not report it as self-employment income on Schedule C.
- You do not report it as an investment distribution, and it will not show up on Form 1099-DIV or 1099-R.
- You typically will not receive a tax form for the draw. Lenders do not issue a 1099 just because you borrowed.
Instead, a HELOC is reflected in your financial life as:
- a higher loan balance on your monthly HELOC statement, and
- interest you may pay (which is a separate issue from whether the proceeds are taxable).
What you might see: Form 1098 for interest
If you pay $600 or more of mortgage interest during the year, your lender or servicer is generally required to send you (and the IRS) Form 1098 (Mortgage Interest Statement). In practice, delivery can vary by servicer and by how the HELOC is set up, so it is smart to check your year-end statement and online tax documents even if you do not receive a paper 1098.
Form 1098 reports interest paid, not proceeds received.
One quick interest note, because it is where people get tripped up: under current rules, mortgage interest is generally deductible only when the debt is used to buy, build, or substantially improve the home that secures the loan, and only if you itemize. If you used the HELOC for other purposes, the interest may be limited or may fall under other rules. The proceeds are still not taxable, either way.
If you want a deeper dive, see our HELOC interest deduction coverage on the site.
When HELOC debt can become taxable
The most common time a HELOC becomes tax-relevant on the principal side is when you do not have to pay it back.
If a lender forgives, cancels, settles, or discharges part of your HELOC balance, the IRS may treat the canceled portion as cancellation of debt (COD) income.
Why? Because if you borrowed money and later are no longer legally required to repay it, your net worth effectively increases.
There are a few rare situations where the story is not as simple, for example disputed debt, identity theft, or situations where the amount is later corrected. Those are not everyday cases, but they are another reason to read lender notices carefully.
Situations that can trigger COD income
- Negotiated settlement: You pay less than you owe and the lender forgives the rest.
- Loan modification: Part of the balance is forgiven as a condition of restructuring.
- Debt discharge after default: The lender writes off a portion and issues tax reporting.
- Foreclosure or short sale: Depending on whether the debt is recourse or nonrecourse, you may be dealing with COD income, gain or loss on the home disposition, or a mix of both.
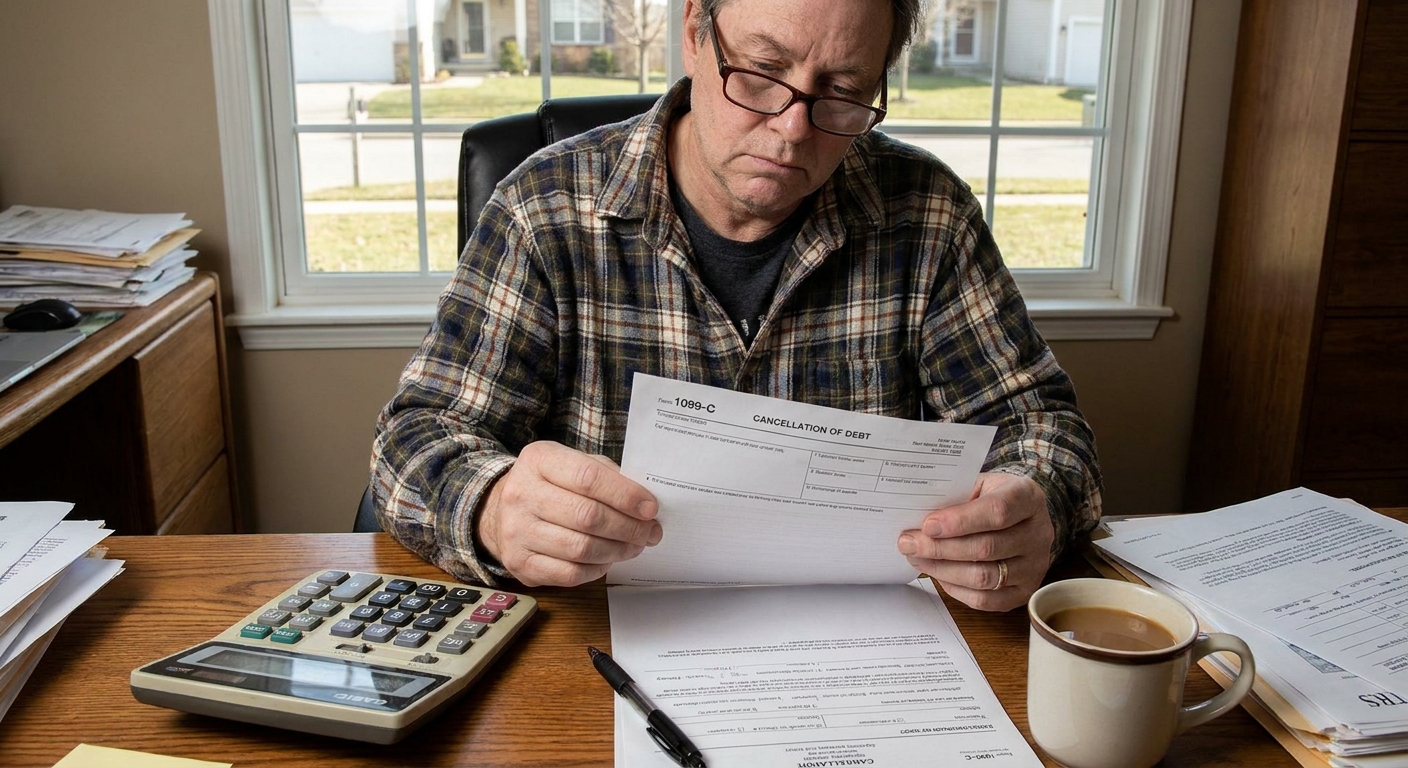
Form 1099-C is the form to watch for
If $600 or more of debt is canceled, the lender may be required to issue Form 1099-C (Cancellation of Debt) in many common situations. That said, not every cancellation results in a 1099-C, and you can still have taxable COD income even if you never receive a form.
If you do get a 1099-C, treat it as a stop and verify moment. Confirm the amount, the date, and that the borrower information is correct. Then confirm whether an exclusion applies and whether you need to file additional paperwork (often Form 982).
Exclusions that can reduce COD tax
There are scenarios where canceled debt is excluded from income under IRS rules. Two of the most common are:
- Bankruptcy exclusion: If the debt was discharged in a Title 11 bankruptcy case, it is often not taxable.
- Insolvency exclusion: If you were insolvent immediately before the cancellation (your total debts exceeded your total assets), you may be able to exclude some or all COD income.
You may also hear about special rules for certain canceled mortgage debt on a primary residence. The important nuance is that these rules are typically tied to qualified principal residence indebtedness and often focus on acquisition-type debt. A HELOC that was used for things like credit cards, tuition, or business expenses may not qualify.
These rules are technical and fact-specific. If you get a 1099-C tied to a HELOC, it is worth getting professional tax help to confirm whether an exclusion applies and to file any required forms correctly.
Keeping HELOC draws clean in your records
In real life, tax trouble usually starts with messy bookkeeping, not malicious intent. This is especially true for entrepreneurs who use a HELOC as a flexible cash tool.
To clearly show that a deposit was a loan draw, not income, keep records that create a clean paper trail.
What to keep
- HELOC agreement and closing documents showing the credit limit, terms, and collateral.
- Monthly HELOC statements showing draws, repayments, interest, and the outstanding balance.
- Bank deposit records that match the HELOC draw amounts and dates.
- Settlement letters or payoff statements if you refinanced, sold the home, or paid off the line.
- Any lender correspondence about forgiveness, settlement, or charge-off, plus any 1099-C received.
If you are self-employed
If you move HELOC funds into a business checking account, label that transfer in your accounting software as something like “Owner loan proceeds” or “Loan funding” rather than sales income.
Also, keep in mind: business use does not make the proceeds taxable, but it can affect where and how interest is deducted. In general, tax rules care about tracing the use of the funds, so clean records matter.
I recommend maintaining a simple memo log (a spreadsheet is fine) with:
- date of draw,
- amount,
- where it was deposited, and
- what it was used for.
This is not about over-documenting. It is about being able to answer one question quickly if you are ever asked: “Why is this deposit not income?”
Edge cases people ask about
Is a HELOC draw taxable if I use it to pay off credit cards?
No. Paying off credit card debt with a HELOC is a refinance-style move: you swapped one debt for another. The draw itself is still not income.
Is a HELOC draw taxable if I use it for a down payment?
Still no. You borrowed funds for the down payment. That is not income. Just make sure you can qualify and manage the payment risk, because layering debt is where financial stress usually begins.
Is a HELOC draw taxable if I invest it?
The draw is not income. But any investment gains could be taxable depending on the account and the type of gain (capital gains, dividends, interest). That is separate from the HELOC proceeds.
Is a HELOC draw considered earned income for IRA purposes?
No. Borrowed money is not earned income. It does not create eligibility to contribute to an IRA or increase contribution limits. IRA contributions generally require compensation such as wages or net self-employment income.
Quick checklist
- Do not report HELOC proceeds as income just because the cash hit your bank account.
- Watch for Form 1099-C if you settled, defaulted, or had any portion forgiven.
- Keep your HELOC statements and draw records with your tax documents.
- Separate loan deposits from revenue in business bookkeeping.
- Ask for help if you receive a 1099-C or have a foreclosure, short sale, or debt settlement. Exclusions may apply, but they often require specific forms and correct timing.
FAQ
Are HELOC proceeds taxable income?
Usually no. HELOC proceeds are borrowed money and are not taxable when received.
Do I have to report a HELOC draw on my tax return?
Typically no. The draw itself usually does not appear on your return. Interest reporting and deductibility are separate topics.
When can a HELOC create taxable income?
If some of the HELOC balance is forgiven or canceled, the canceled amount may be treated as cancellation of debt income unless an exclusion applies.
What form do I get if my HELOC debt is canceled?
Often Form 1099-C, especially if $600 or more is canceled. Not every situation produces a 1099-C, and taxable COD income can exist even without one, so it is worth reviewing any cancellation paperwork carefully.
One last practical thought
A HELOC can be a smart tool, especially for smoothing cash flow or funding a project with a clear payoff. But in tax land, simplicity wins. Treat HELOC proceeds like what they are: loan funding. Keep the paperwork. And if forgiveness, settlement, or foreclosure enters the story, slow down and get guidance before you file.