When I was growing up, I watched my parents juggle working capital needs for their agricultural supply business with the reality that our house was the one truly stable asset on the balance sheet. That experience made one thing very clear early: debt is not just about the interest rate. It is also about the rules attached to it, and taxes are a big part of those rules.
A HELOC can be a flexible tool, but the tax deduction is not automatic. Whether HELOC interest is deductible depends on how you use the money, not on whether the debt is called a HELOC or a home equity loan.
Important: HELOC deductibility has changed over time and can change again. The rules below reflect current law as applied under the Tax Cuts and Jobs Act framework. If you are reading this for a specific filing year, confirm the details in IRS Publication 936 or with a tax professional.
The short answer
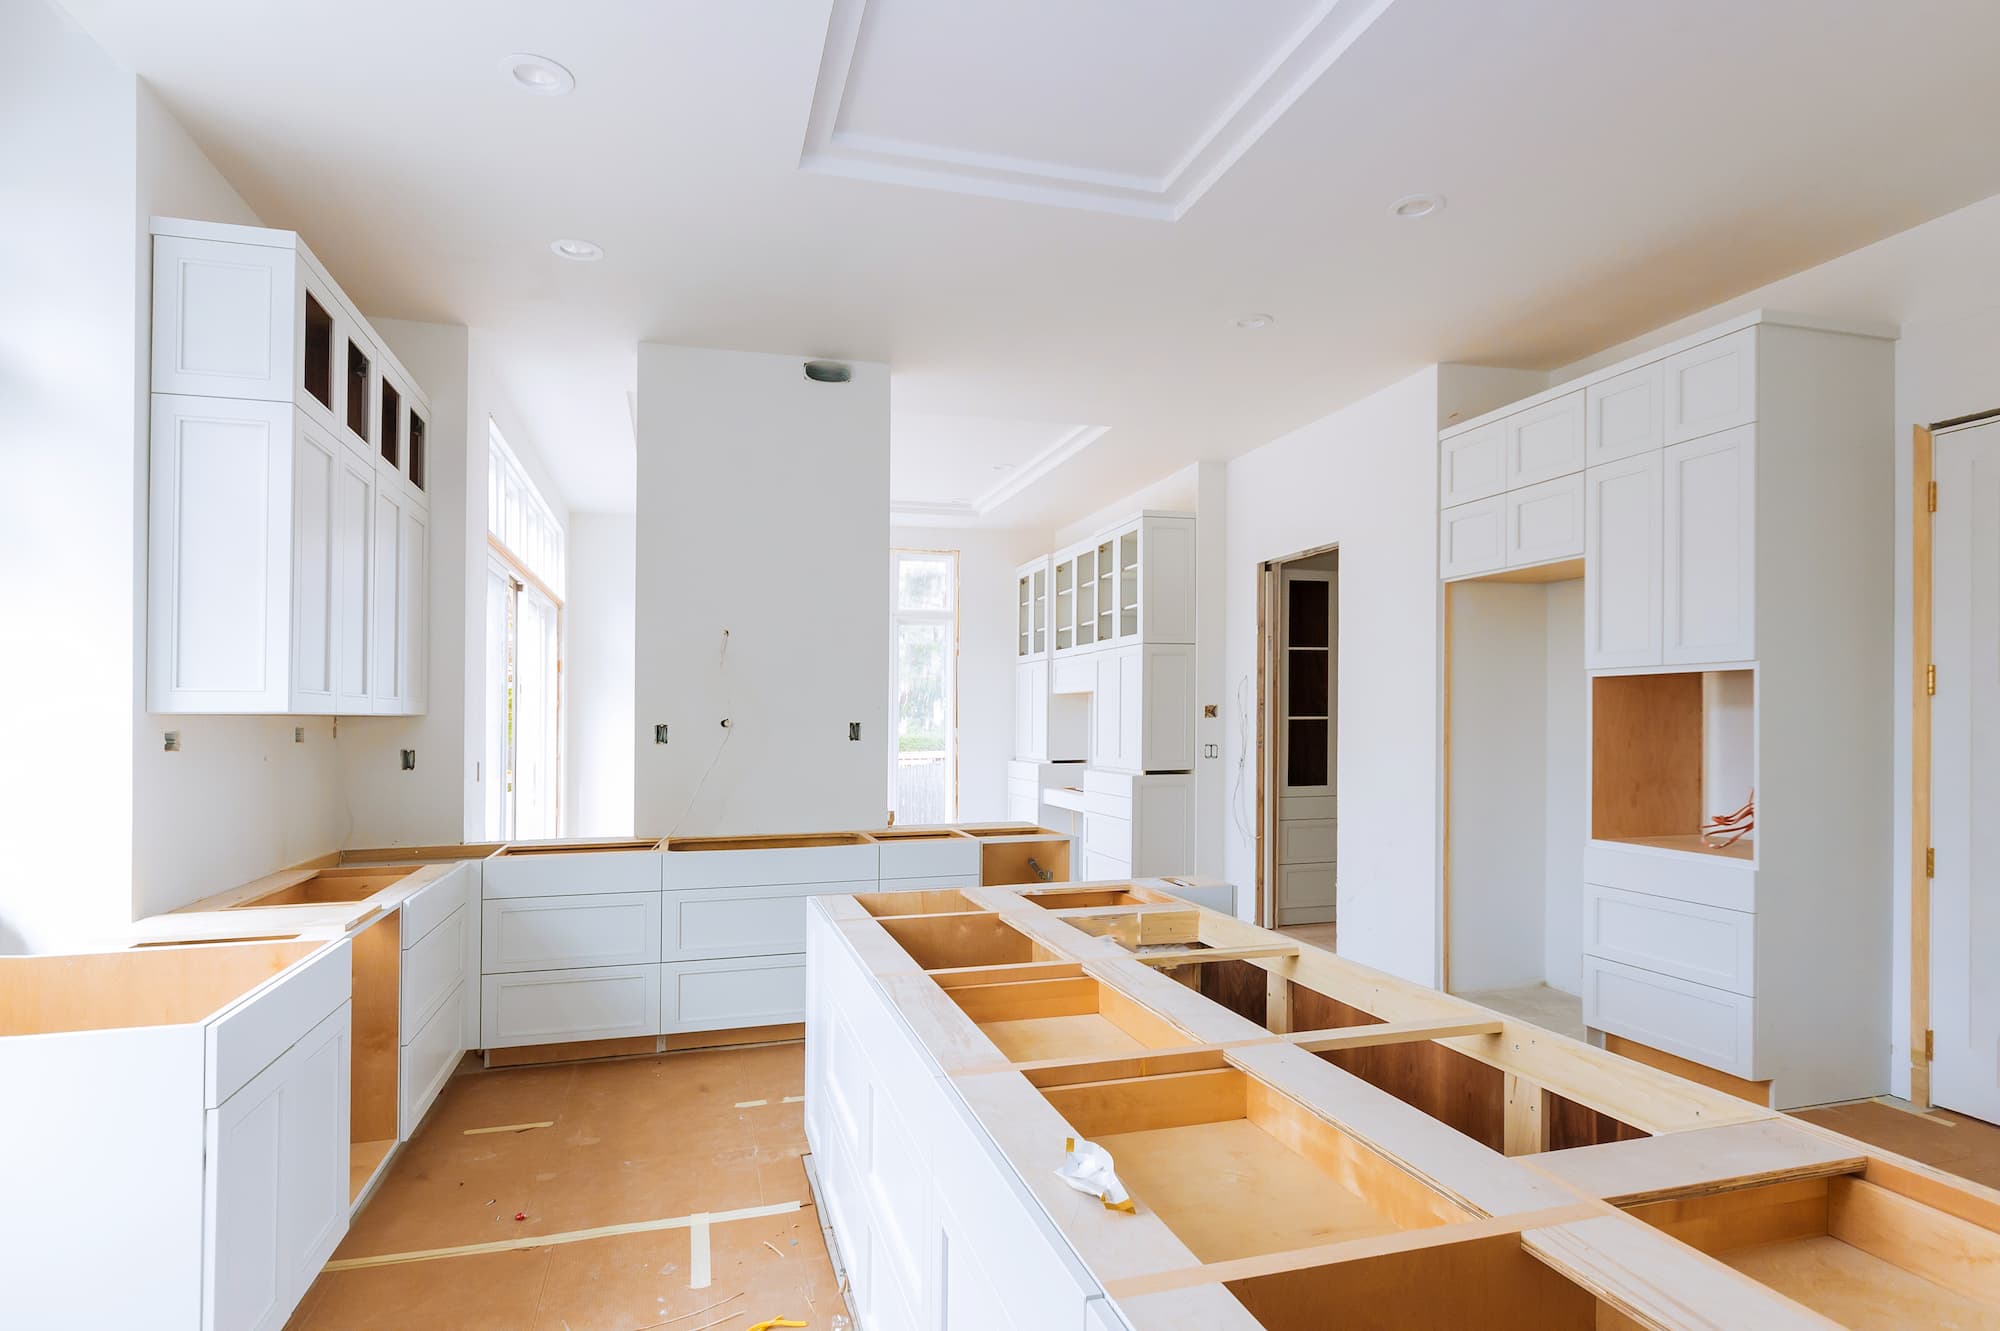
HELOC interest is tax deductible only if the borrowed funds are used to buy, build, or substantially improve the home that secures the HELOC, and you itemize deductions on Schedule A.
If you use HELOC funds for other purposes like paying off credit cards, covering tuition, buying a car, or funding a business, the interest is generally not deductible as home mortgage interest, even though the loan is secured by your home.
What the IRS allows
For most homeowners, the relevant bucket is home mortgage interest on home-acquisition debt. Under current rules, interest is deductible when:
- The debt is secured by a qualified home, meaning your main home and, if applicable, one other home you choose to treat as a second home (as long as it meets the IRS rules), and
- The proceeds are used to buy, build, or substantially improve the same home that secures the loan.
This is the key point people miss: it is not enough that your home is collateral. The use of the funds must match the home that backs the debt. If the HELOC is on your primary home but you use the money to renovate a different property, that interest generally does not qualify as deductible qualified residence interest for the HELOC-secured home.
What counts as a qualified home
Your main home is where you typically live most of the time. A second home can also qualify, but the IRS has rules, including personal-use requirements, that can matter a lot if the property is also rented out.
If a property is a pure rental (or does not meet the second-home tests), the interest treatment often shifts away from Schedule A and into rental or investment interest rules. That can be completely legitimate, but it is a different analysis than “HELOC interest is deductible on Schedule A.”
Substantial improvement
Think of “substantially improve” as a project that adds value, extends the useful life of the home, or adapts it to new uses. Examples that are commonly considered improvements include:
- Kitchen remodel
- Bathroom addition or major renovation
- Replacing the roof
- Finishing a basement
- Building a deck or adding a room
- Major HVAC replacement
- Accessibility upgrades like ramps or widened doorways
Counterexamples help here. Routine maintenance is often not a substantial improvement by itself, even if it is necessary. Examples include:
- Painting one room
- Fixing a small leak
- Replacing a broken windowpane
- Minor patch-and-repair work
Smaller repairs can still be part of a broader improvement project, but that is where documentation and clear scope matter.
When HELOC interest is not deductible
Even if your HELOC is secured by your home, the interest is generally not deductible as home mortgage interest when the money is used for:
- Paying off credit cards or personal loans
- Buying a car or boat
- Paying tuition or other education costs
- Vacations, weddings, or living expenses
- Investing in stocks, crypto, or private deals
- Starting or funding a business (see business note below)
A common scenario: someone uses a HELOC to consolidate high-interest debt. That may be a smart cash flow move, but it does not usually create a mortgage interest deduction.
The tracing rule
If you take one thing from this article, make it this: the IRS cares what the HELOC proceeds were used for, and you should be able to prove it.
This is often described as tracing. In practice, it means you need a paper trail that connects:
- HELOC draw (date and amount)
- Where the money went (the account it landed in)
- What it paid for (contracts, invoices, receipts)
- That the spend was for the home securing the HELOC
If you mix HELOC proceeds into a general checking account that also pays your normal bills, tracing becomes harder. Harder does not mean impossible, but it raises the odds you cannot support the deduction if questioned.
What records to keep
To defend a HELOC interest deduction, keep records that make the story obvious to a third party who knows nothing about your life.
HELOC and interest documents
- Your HELOC agreement and opening disclosures
- Monthly statements showing draws and payments
- Form 1098, if issued by your lender (some lenders do not issue one in certain cases, including when interest is below reporting thresholds)
Proof of where the money went
- Bank statements showing the draw deposit
- Copies of checks or electronic payments made to contractors or suppliers
Proof of improvement work
- Signed contracts and change orders
- Itemized invoices
- Receipts for materials
- Permits and inspection sign-offs, if applicable
- Before-and-after photos can help corroborate timing and scope
One HELOC, two uses
Let’s say you have an $80,000 HELOC on your primary home.
Example A: Renovation use
You draw $50,000 to remodel your kitchen in the same home that secures the HELOC. You pay the contractor in three installments directly from a separate account used only for renovation expenses.
Result: The interest attributable to that $50,000 portion is generally eligible to be treated as deductible home mortgage interest, assuming you itemize and stay within the IRS limits for home-acquisition debt.
Example B: Non-home use
A month later, you draw $20,000 to pay off a credit card and cover a family trip. The funds hit your normal checking account and you pay several unrelated bills.
Result: Interest attributable to that $20,000 portion is generally not deductible as home mortgage interest.
In other words, the same HELOC can produce partly deductible and partly nondeductible interest. Your job is to document and calculate it correctly.
Allocating interest for mixed use
If your HELOC has mixed uses, you generally allocate interest based on how the proceeds were used and the outstanding balances tied to those uses. In plain terms:
- Track each draw and label it by purpose.
- Track repayments and how they reduce the outstanding balance over time.
- Allocate the interest between the deductible and nondeductible portions based on the balances attributable to each use.
This is where a clean, separate-account setup can save you hours, and it is also where tax software or a CPA can be worth the cost if your draws and paydowns are messy.
Do you have to itemize?
Yes. HELOC interest that qualifies as home mortgage interest is claimed on Schedule A as an itemized deduction.
If you take the standard deduction, you typically will not see a tax benefit from otherwise deductible HELOC interest. Practically, it is worth running the numbers both ways, especially if your itemized deductions are close to the standard deduction threshold.
Debt limits
Even when your HELOC funds qualify as home-acquisition debt, the deductible interest is still subject to IRS limits.
- For many taxpayers, interest is generally deductible only on up to $750,000 of qualified residence loans ($375,000 if married filing separately) for acquisition debt incurred after December 15, 2017.
- Higher limits may apply to certain older “grandfathered” acquisition debt incurred on or before that date (commonly referenced as $1,000,000, or $500,000 if married filing separately), depending on the facts.
These rules can get technical fast, especially if you refinanced, have multiple homes, or have a HELOC plus a first mortgage. When in doubt, IRS Publication 936 is the best starting point.
HELOC money used for a business
Using HELOC funds for a business typically means the interest is not deductible as home mortgage interest.
However, under interest tracing principles, it may be possible for some taxpayers to treat that interest as business interest or investment interest depending on exactly how the proceeds were used and how the activity is reported. Those categories come with their own limitations and documentation requirements, and some taxpayers may run into additional constraints under the business interest rules.
The safe takeaway: business use does not make the interest disappear, but it moves you into a different set of rules than Schedule A mortgage interest.
Best practices
- Keep renovation draws separate. Consider sending HELOC draws into a dedicated account used only for the improvement project.
- Pay contractors directly from that dedicated account when possible.
- Save documentation as you go. Waiting until March or April to reconstruct a paper trail is how details get lost.
- Label files clearly. Use a simple naming system like “2026-05 HELOC draw 15k bathroom invoice.”
- Track mixed-use draws. If you used one draw for two purposes, document how much went to each.
FAQ
Is HELOC interest tax deductible if I use it to pay off credit cards?
Generally no. Paying off credit cards is not buying, building, or substantially improving the home that secures the HELOC.
Is HELOC interest tax deductible if I use it to remodel my home?
Often yes, as long as the remodel is for the same home that secures the HELOC, you can substantiate the spending, you stay within the applicable debt limits, and you itemize deductions.
What if my lender did not send a Form 1098?
You can still potentially deduct qualifying interest if you have reliable records, such as year-end statements and payment history showing interest paid. The deduction is based on what you paid and what it was used for, not solely on whether you received a form.
Can I deduct HELOC interest on a rental or second home?
A second home can be a qualified home, but it has to meet IRS rules. If the property is a pure rental or does not qualify as a residence under the second-home tests, the interest is typically handled under rental or investment rules rather than as Schedule A mortgage interest. This is a good place to get tax advice if you are not sure which bucket you are in.
The takeaway
A HELOC can be a great financial tool, but the tax deduction is conditional. If you want HELOC interest to be deductible, plan the spending path before you draw the money. Keep the trail clean, keep the paperwork, and treat each draw like it needs to tell a simple story: this money improved the home that secures the loan.
If your HELOC has mixed uses or you are unsure whether your project qualifies as a substantial improvement, a quick check-in with a CPA or Enrolled Agent can save you far more than it costs.