When my parents were running their agricultural supply business, they treated every loan like a living thing. Not because they loved debt, but because one loan could quietly “shape-shift” into three different purposes over a year: inventory this month, a roof repair next month, then a cash squeeze in the slow season. That lesson shows up again and again in tax work, especially with HELOCs.
If your HELOC is secured by a rental property, the interest can be deductible on your rental tax return. The catch is that the deduction generally follows how you used the proceeds, not what the line is “attached to.” That is what people mean when they talk about interest tracing.
Below is how rental-interest tracing works when a HELOC is secured by a rental and the money is used on that rental, how it differs from qualified-residence interest, and how to handle a mixed-use draw that must be split.
The big rule: Use of funds drives the deduction
For rental real estate, the most practical way to think about deducting HELOC interest is this:
- Use the HELOC money for the rental and the interest is generally treated as a Schedule E rental expense.
- Use the HELOC money for something else and the interest generally belongs somewhere else on your tax return, or it may not be deductible at all.
That is why two investors can have the same HELOC secured by the same rental address and have totally different tax outcomes.
Two guardrails: Even when interest is properly traced to the rental, it can still be affected by limitations such as passive activity and at-risk rules. And in certain build or major improvement situations, some interest may need to be capitalized instead of deducted currently.
When HELOC interest is usually Schedule E
HELOC interest tied to a rental property is typically handled on Schedule E when the borrowed funds are used for costs connected to that rental activity, for example:
- Repairs and maintenance (fixing a leak, replacing broken windows, patching drywall)
- Operating costs you pay for the rental (insurance, utilities you cover, HOA dues) when the HELOC funds actually paid those bills
- Capital improvements to the rental (a remodel, new roof, HVAC replacement)
- Acquisition costs tied to buying a rental (for example, certain closing costs) if you used borrowed funds for them
Important nuance: Repairs are generally deducted as current expenses, while improvements are typically capitalized and depreciated. Interest on money borrowed for the rental is generally treated as a rental expense, but there are scenarios where interest is required to be capitalized (added to the basis of the project) rather than deducted right away.
If you are doing a major renovation, new construction, or a long project where the property is not yet in service, ask a tax pro whether you have capitalized interest issues. Getting this wrong can create messy amended returns later.
Schedule E vs qualified-residence interest
People often mix up rental interest with qualified-residence interest, especially because a HELOC sounds like “home” financing.
Qualified-residence interest
Qualified-residence interest rules generally apply to interest on debt secured by your main home or a second home that you use as a residence, within IRS limits and requirements. This is the category that may show up on Schedule A if you itemize.
Schedule E interest
When a property is held out for rent, interest that is connected to the rental activity is generally handled on Schedule E. In plain English: it is treated as a cost of earning rental income.
One important wrinkle: some properties are both personal-use and rental in the same year (think vacation home rules, or a former residence that you started renting out). In those cases, the interest and other expenses can require allocation based on rental days vs personal-use days, and the same property can involve both Schedule E and Schedule A treatment depending on the facts.
Cleanest scenario: 100% for the rental
If you draw from the HELOC and the funds are used entirely for that same rental property, you are in the easiest recordkeeping position.
Example:
- You open a HELOC secured by Rental Property A.
- You draw $25,000 and pay contractors to replace the roof on Rental Property A.
- You pay $1,800 of HELOC interest during the year.
In many straightforward cases, that interest is treated as a rental expense on Schedule E because the debt proceeds were used for the rental.
Documentation tip: Keep the draw history and match it to invoices and proof of payment. In an audit, the story you want your records to tell is simple: “Borrowed X on this date, paid these rental bills.”
Mixed-use draws: Splitting the interest
This is where people get tripped up, especially with HELOCs because they are so easy to tap in multiple bursts.
If a single draw is used for both rental and non-rental purposes, the interest generally needs to be allocated between uses based on tracing.
Example: One draw, two purposes
Say you take a $40,000 HELOC advance secured by your rental:
- $28,000 goes to a kitchen rehab at the rental
- $12,000 goes toward a personal expense (for example, a family trip or paying off a personal credit card)
In that case, you generally cannot deduct 100% of the HELOC interest on Schedule E. The portion tied to the rental use is typically the part that belongs on Schedule E.
A simple allocation approach, if the dollars left the HELOC at the same time and you can trace exactly where they went:
- Rental portion: 28,000 / 40,000 = 70%
- Non-rental portion: 12,000 / 40,000 = 30%
If you paid $2,000 of interest for the year on that balance, you would generally treat $1,400 as rental interest (Schedule E) and the remaining $600 as non-rental interest.
What makes this hard: With revolving credit, balances change as you pay the line down and re-borrow. Once you have paydowns and multiple draws, a simple percentage split may not match reality. Many taxpayers end up doing a draw-by-draw tracing method, and in more active HELOCs it can mean month-by-month or average balance computations. This is where a spreadsheet, or help from a preparer, is worth its weight.
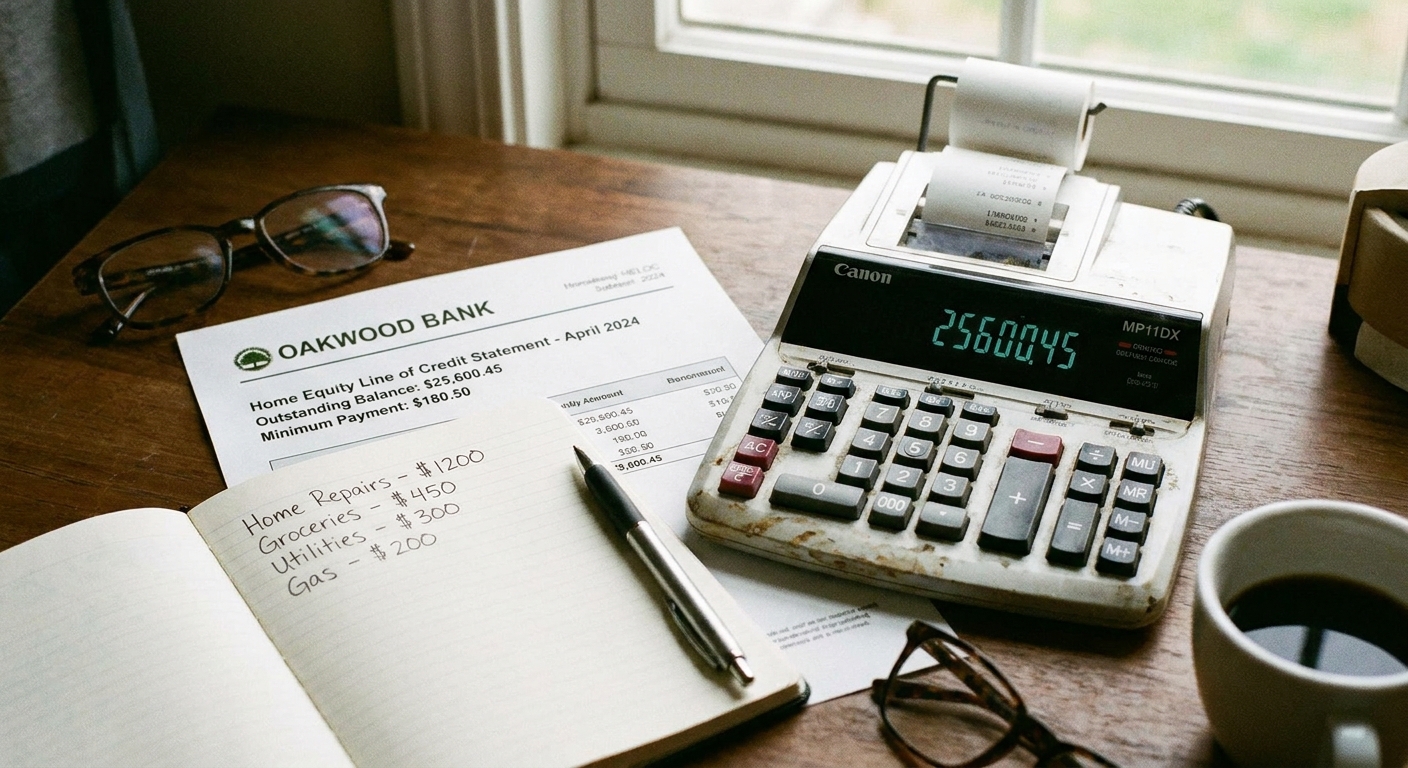
One HELOC used across multiple properties
It is common for landlords to use one HELOC (secured by one property) to fund work on another property. The tracing concept is still about the use of the funds, but the bookkeeping burden increases because now you are allocating by property.
Practically speaking, you want to be able to answer:
- Which draws went to Property A, Property B, and so on?
- How much interest is attributable to each bucket over the year?
Some investors simplify this by using separate financing sources or separate HELOCs for separate projects. That is not always possible, but it does reduce ambiguity.
If the property changes use during the year
A very real scenario: you live in a home, open a HELOC, then later convert the home to a rental. Or you buy a rental and later move in.
Interest treatment can shift when the property shifts, and it is not always all-or-nothing. Depending on timing and facts, you may have periods where interest is personal (often not deductible under current law), periods where it is qualified-residence interest (Schedule A if you itemize and the debt qualifies), and periods where it is rental-related (Schedule E). If you are near a conversion date, keep clean notes on when the property was placed in service as a rental and how the HELOC funds were used.
Where non-rental HELOC interest might go
If HELOC funds were not used for the rental, here are common outcomes:
- Personal spending: personal interest is generally not deductible under current law.
- Investments: if you used HELOC proceeds to buy taxable investments, the interest may be deductible as investment interest, subject to limits and typically reported with Form 4952.
- Business use: if you used funds in an active trade or business, the interest may be business interest, with its own set of rules.
The theme stays the same: the debt follows the use of the proceeds.
Fees, points, and other HELOC costs
Not every charge on a HELOC statement is “interest.” Annual fees, origination fees, and similar charges can have different tax treatment than interest. Some fees may be deductible as an expense depending on what they are and what the line is used for, while others may need to be spread out or handled as a cost of obtaining financing. If the dollar amounts are meaningful, flag the fee line items for your preparer instead of assuming they go in the same bucket as interest.
Recordkeeping: Making tracing defensible
You do not need a perfect system, but you do need a consistent one. If you want your deduction to survive questions, focus on documentation that ties dollars borrowed to dollars spent.
- HELOC statements showing draw dates and amounts
- Bank records showing where the draw landed (and where it went next)
- Invoices and contracts for rental work
- Canceled checks or card receipts for payments
- A simple log mapping each draw to a purpose and property
If the draw went into a general checking account that also pays personal bills, keep especially clean backup. In practice, commingling is where tracing gets messy fast.
Common confusion points
“But the HELOC is secured by the rental. Doesn’t that make it rental interest automatically?”
Not automatically. Security matters for lending, but deductibility is commonly driven by use of proceeds. The IRS cares about what the debt funded.
“My lender did not send a Form 1098. Can I still deduct the interest?”
Potentially, yes. Some lenders do not issue a Form 1098 for certain lines or may only issue it when specific reporting thresholds and requirements are met. The absence of a form does not, by itself, mean interest is non-deductible. It does mean your documentation needs to be solid, and your year-end statements matter.
“Is the interest deduction limited by passive loss rules?”
It can be. Schedule E deductions, including interest, flow into the broader rental-income, at-risk, and passive-activity framework. Even if the interest is properly traced to the rental, you might not be able to use the loss this year depending on your income and participation. That is a different question than whether the interest is a valid rental expense in the first place.
Quick checklist
- Did the HELOC proceeds go to rental-related costs? If yes, you are likely in Schedule E territory.
- Can you trace each draw to specific payments? If not, clean up your records before filing.
- Was any draw mixed-use? If yes, allocate interest by use and be ready for more detailed math if you had paydowns and re-borrows.
- Was the property partly personal and partly rental? If yes, consider vacation home rules, conversions, and allocation by days and use.
- Were there big build or improvement projects? If yes, ask whether any interest should be capitalized.
FAQ
Is interest deductible on a HELOC secured by a rental property?
Often, yes, if the HELOC funds are used for the rental activity and you can trace the money. In many straightforward cases, the interest is treated as a Schedule E expense, subject to limitations like passive activity and at-risk rules.
If I use a HELOC draw partly for the rental and partly for personal spending, what happens?
You generally split the interest between uses based on tracing. The rental-related portion is typically the part that belongs on Schedule E. The personal-use portion is generally not deductible under current law.
Is this the same as deducting HELOC interest on my primary home?
No. Qualified-residence interest is a different category and typically relates to your main home or second home (and usually Schedule A if you itemize and the debt qualifies). Rental-related interest is typically handled on Schedule E when it is tied to the rental activity. If a property is both personal-use and rental, you may have to allocate.
My bottom line
A HELOC secured by a rental property can absolutely produce deductible interest, but you earn that deduction with clean tracing. If the borrowed money went into the rental, the interest usually lives on Schedule E. If the draw was mixed-use, you split it. And if the funds wandered through a personal account with no paper trail, you are inviting unnecessary stress.
If you want, tell me how many draws you took and what each draw paid for, and I can walk you through how to think about the split in plain English before you hand it to your tax preparer.