If you are considering a HELOC, you are probably not asking out of curiosity. You are asking because there is a kitchen remodel quote expiring, a surprise tax bill, a business opportunity that needs cash, or you are consolidating high-interest debt and you want the interest clock to start working in your favor.
In my years advising both businesses and households, the biggest stress point is rarely the interest rate. It is timing. A HELOC is not instant money, and the process can feel like a mini mortgage.
Here is the realistic answer: many HELOCs fund in about 2 to 6 weeks from application to having access to the line. Some lenders can do it faster with automated valuations, complete documents, and clean title. Others stretch longer when underwriting needs extra documentation, title work takes time, or an appraisal is backlogged.
Typical HELOC timeline at a glance
Every lender has its own workflow, but most HELOCs move through the same phases. These ranges assume you are applying for a primary residence HELOC with a large bank, credit union, or online lender.
- Application and document upload: 1 to 3 days
- Initial review and disclosures: 1 to 5 days
- Valuation (appraisal or automated value): 3 days to 3 weeks
- Underwriting and conditions: 3 days to 2+ weeks
- Closing and signing: 2 to 10 days
- Right of rescission (if applicable): 3 business days
- Account setup and access to funds: same day to 3 days after rescission
Bottom line: in a best-case file with a fast valuation and minimal conditions, you might be finished in about 10 to 21 days. A more typical range is 2 to 6 weeks. If you have a complex income profile, a full appraisal, or title issues to clear, 30 to 45+ days is not unusual.
Step-by-step: from application to funding
1) Application: usually 15 minutes to an hour, then 1 to 3 days to assemble the file
The actual application is often fast. The slower part is providing a complete, readable document package and responding quickly to follow-up questions.
Some lenders offer a preliminary decision based on a soft credit pull and stated income. Others run a hard pull earlier. Either way, the real timeline starts once they have the documents they need to verify everything.
2) Disclosures and initial review: 1 to 5 days
Early in the process you will typically receive disclosures, rate and fee information, and sometimes an initial list of required documents called conditions. If you return signed disclosures immediately and your file is complete, you save days right here.
3) Home valuation: 3 days to 3 weeks
Your lender needs a value for your home to calculate how much equity is available. This step varies the most.
- Automated Valuation Model (AVM): sometimes same day to a few days, if the lender accepts it for your property type and line amount.
- Desktop appraisal: often about 3 to 10 days.
- Full appraisal (in-person): commonly 1 to 3 weeks depending on appraiser availability and local volume.
Unique properties, rural locations, multi-unit homes, or major recent renovations without permits can push this step longer because the appraiser may need more comps or documentation.
4) Underwriting: 3 days to 2+ weeks
Underwriting is where the lender verifies your income, debts, credit profile, and property details, then decides the final terms and whether they need anything else from you.
This is also where delays tend to happen because underwriting is not just a checklist. The underwriter is assessing risk. If something looks inconsistent, they will pause the file and ask for clarification.
Common underwriting conditions that add time include:
- Updated pay stubs or a missing page from a bank statement
- Proof that a large deposit is not borrowed funds
- Explanation letters for credit inquiries, late payments, or employment gaps
- Verification for self-employment income
- Clarification of property taxes, HOA dues, or homeowners insurance
- Title questions, such as an old lien that still shows as open
5) Closing: 2 to 10 days
Once underwriting signs off, your lender prepares the closing documents. Some HELOCs close electronically. Others require a notary visit.
Timing depends on how quickly the closing team can generate documents, how quickly you can schedule a signing, and whether there are title-related items to clear.
6) The rescission period: 3 business days (common on primary residences)
For many HELOCs secured by a principal residence, federal Truth in Lending rules provide a three-business-day right of rescission after closing disclosures are delivered and you sign. During this window you can cancel for any reason.
This waiting period is a built-in part of the timeline for most owner-occupied, non-purchase transactions. It does not apply in every situation, and timing rules can get technical because the clock depends on business-day definitions and proper delivery of required notices. Your lender’s closing team can tell you exactly what applies in your case and when funds will be available.
7) Funding and access: same day to 3 days after rescission
After rescission ends (when it applies), the lender finalizes setup so you can draw on the line. Access can look like:
- An online transfer to your checking account
- A HELOC checkbook
- A debit card tied to the line (less common)
If your plan depends on paying a contractor or making a time-sensitive payoff, ask your lender early how draws work, limits on initial draws, and whether there is a holding period for large transfers.
What can speed up your HELOC approval
The fastest HELOCs tend to have two things in common: a straightforward borrower profile and a clean property record.
- High credit score and low existing debt: fewer questions, fewer conditions.
- W-2 income: often simpler to verify than self-employment income.
- Digital document upload: less back-and-forth than mailing.
- AVM-eligible property: skipping a full appraisal can remove weeks.
- Quick responses: if underwriting asks for something, returning it within 24 hours can keep your file in the active queue.
- Clear title history: no unresolved liens or ownership quirks.
What typically causes delays
Delays are not always your fault. Some are system-wide, like appraisal backlogs. But many are preventable.
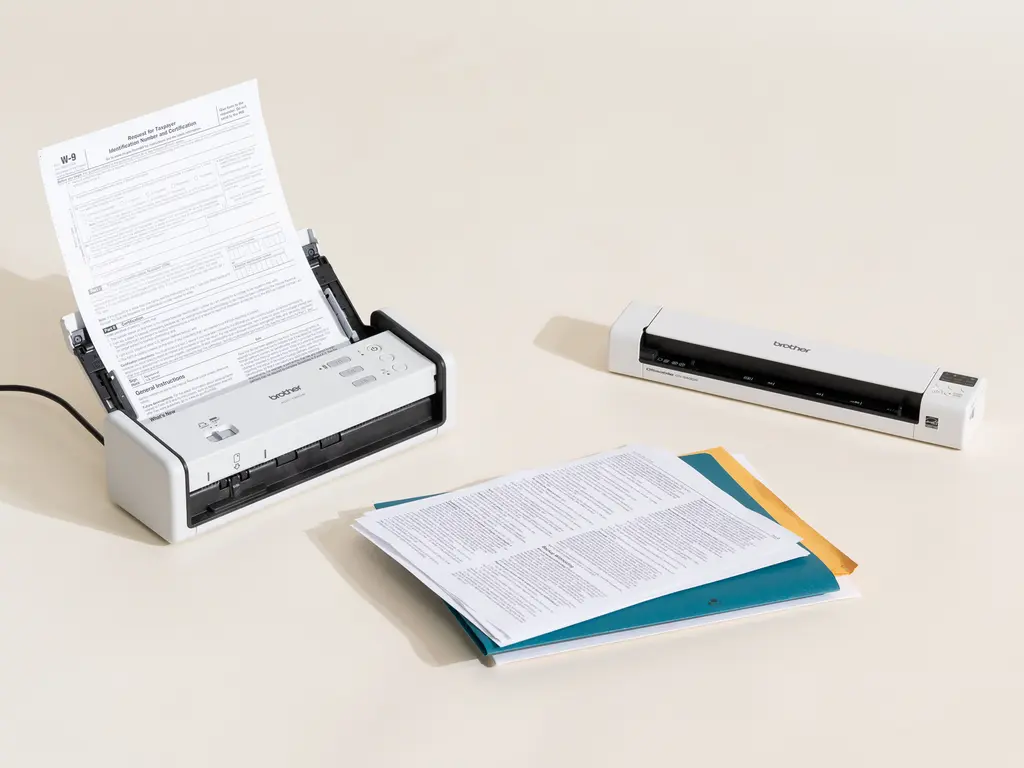
- Incomplete documents: missing pages, cropped screenshots, or statements that do not show your name and account number.
- Income that is harder to verify: self-employment, commissions, bonuses, multiple jobs, or recent job changes.
- Property complications: condos with insufficient documentation, multi-family units, or unusual comps.
- Title issues: old HELOCs not properly released, judgments, or errors in how names appear on title.
- High combined loan-to-value (CLTV): if you are pushing the lender’s maximum, underwriting often gets stricter.
- Busy season: spring and summer can be heavy for appraisers and mortgage departments.
How to prepare documents so you do not lose a week to back-and-forth
I grew up watching my parents juggle business loans and seasonal cash flow for their agricultural supply company. The lesson that stuck with me is simple: lenders move faster when your paperwork tells a clean story. A HELOC is no different.
Here is a practical pre-application checklist you can assemble in one sitting.
Common documents lenders ask for
- Identification: government-issued ID
- Proof of income: recent pay stubs, W-2s, and sometimes two years of tax returns
- If self-employed: two years of personal and business tax returns, year-to-date profit and loss statement, and sometimes a balance sheet
- Asset statements: bank statements and possibly retirement or brokerage statements
- Mortgage information: most recent mortgage statement for your first lien
- Homeowners insurance declarations page
- Property tax bill
- HOA statement: if applicable
Two small moves that prevent big delays
- Send full statements: all pages, even blank ones, in a single PDF if possible.
- Flag large deposits: if a statement shows an unusually large deposit, be ready with a paper trail (sale of an asset, bonus, transfer between accounts).
Costs and terms that can affect timing
Two practical notes I wish more borrowers knew up front:
- Fees can change the pace. Some lenders charge appraisal, title, or recording fees, while others waive certain costs as a promotion. Even when a lender covers the fee, you still may need to wait for the appraisal or title work to be completed.
- “Funding” means access to a line. A HELOC usually has a draw period (when you can borrow and repay) followed by a repayment period (when you pay down the balance). You are not receiving a lump sum unless you choose to draw one.
Also, remember that many HELOC rates are variable, and final pricing can shift based on credit, CLTV, and relationship discounts after underwriting is complete.
Second homes and investment properties
If you are applying on a second home or an investment property, plan for a longer timeline and more documentation. Many lenders have stricter equity limits and additional underwriting steps, and some rules that commonly apply to principal residences can work differently depending on occupancy and loan purpose.
If you need money fast: options to ask about
If your timeline is tight, you may still prefer a HELOC for flexibility, but you should talk to lenders up front about speed.
- Ask whether they can use an automated valuation: this can be the difference between days and weeks.
- Ask about expedited appraisal options: sometimes available for a fee, sometimes not.
- Ask how quickly draws are available after closing: and whether the initial draw has a cap or special steps.
- Consider whether a home equity loan fits better: a lump-sum product may have a similar process, but the structure may match your need better if you are paying for one large, defined expense.
FAQ
Can a HELOC be approved in a week?
It can happen, but it is not the norm. A one-week timeline usually requires an automated valuation, a very straightforward income profile, and a lender that is set up for fast digital closings. Even then, any applicable rescission period can limit how quickly you can access funds on a principal residence.
Does the three-day rescission period always apply?
No. It commonly applies to many owner-occupied, non-purchase HELOCs secured by a principal dwelling, but there are exceptions and transaction-specific details. The safest move is to ask your lender to confirm whether rescission applies and what exact date and time the line will be available.
What is the biggest bottleneck in the HELOC process?
Most often it is the home valuation step or underwriting conditions related to income verification. If you want the fastest possible outcome, focus on a complete document package and quick responses.
Will shopping lenders slow me down?
Not necessarily. If you keep your documents organized and apply within a tight window, you can compare timelines and fees without adding much friction. The bigger risk is starting with a slow lender, waiting two weeks, and then switching after the appraisal queue has already cost you time.
What should I do before applying to reduce delays?
Pull your credit reports for errors, gather full statements and income documents, and confirm you know your current mortgage balance. If you are self-employed, have year-to-date financials ready. And if you recently changed jobs, be prepared to explain the transition.
The practical takeaway
If you plan for 2 to 6 weeks, you will be realistic without being pessimistic. The fastest HELOCs are built on two things you can control: clean documentation and fast responses. The rest is lender workflow, valuation timing, and title clearance.
If you are aiming for a specific deadline, tell the lender on day one and ask what their current turn times are for valuation, underwriting, and closing. A good loan officer will be candid, and that honesty is worth more than an optimistic estimate.